All Categories
Featured

Cheap Health Insurance Plans for 2026
Table of Contents
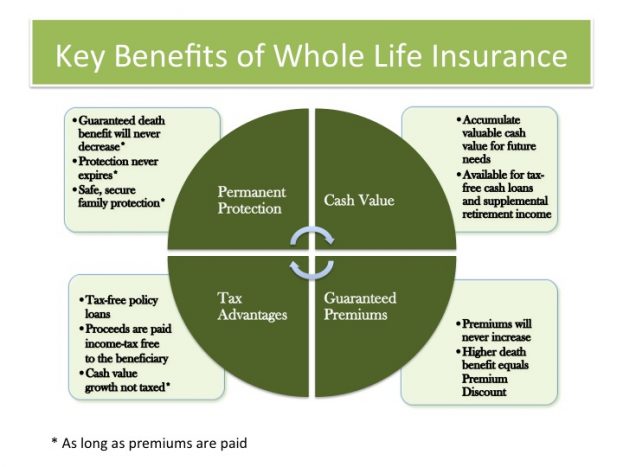
With entire life insurance coverage, you get to choose how your dividends will be used. Here are some of the choices: Purchase additional insurance, which can increase your survivor benefit and accumulated money worth more rapidly than your policy's original warranties. When you utilize your dividend to acquire extra insurance coverage, it sets a brand-new level of guarantee from which the policy's values can't fall from one year to the next Reduce the quantity of premium you owe each year.
Your Northwestern Mutual monetary consultant can assist you figure out the best choice for you. Your policy will accumulate money worth that's guaranteed to grow over time and isn't tied to the stock marketmeaning it will not reduce after a drop in stock costs.
When accessing your money value, you have a few options to consider. You can take a loan against your policy from the insurer. Repayment of the loan is versatile, but interest will accrue. If you pass away with a loan against the policy, your survivor benefit will be minimized by the amount of the loan.
How Whole Life Insurance Operates
This may be a great option if you have a monetary emergency or for bigger, irregular needs, such as remodeling a home. When you surrender your policy, you'll no longer have your insurance coverage. In many cases, when individuals need to access their money worth and no longer require their full death benefit, they give up a part of their policy.
This can likewise be practical from a tax point of view. That's because when you surrender a policy, you'll owe regular income tax on any money value above cash that you've paid in (or "basis"). In this case, you can take all the cash value in your policy, however you likewise surrender all your life insurance.
Insurance in Hemet CA
If you're thinking about tapping into your money worth, your monetary advisor can help you believe through the finest choices for your scenario. Throughout this time, your money value will continue to grow without you owing any cash for your policy.
Life Insurance Strategies for Veteran Families
This advantage means that modifications in your health won't affect your capability to get more insurance down the roadway. Entire life insurance coverage can work alongside other financial tools like investments and deferred income annuities in a complex approach to retirement savings. In reality, a study by EY discovered that retirement methods involving long-term life insurance coverage and deferred income annuities excelled compared with investment-only techniques.
, particularly during down markets.
Otherwise, if you access those accounts while they are down, you 'd essentially be costing a loss.
1 Investopedia. How Whole Life Insurance Coverage Works. Upgraded May 07, 2025. . Accessed March 26, 2026. Material within this short article is offered basic informational functions and is not offered as tax, legal, health, or financial recommendations for anybody or for any particular circumstance. Companies, staff members, and other people need to call their own advisors about their situations.
Lowest Term Life Insurance Quotes Today
Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100.
B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In New York City, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York City, Policy: NYQ60100M. Not offered in VA. Invoice of accelerated survivor benefit may affect eligibility for public support programs. Benefits may likewise be taxable, and are not anticipated to get the same favorable tax treatment as other kinds of accelerated survivor benefit that may be readily available.

Latest Posts

Cheap Individual Health Insurance Quotes in the US
How Whole Life Insurance Works

Comparing Term and Whole Life Insurance Strategies