All Categories
Featured

The Mechanics of Whole Life Coverage
1 Investopedia - How Whole Life Insurance Coverage Works. Upgraded May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance coverage: Pros, cons & who it's right for. Updated March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance Coverage? (& How Does it Work?) Upgraded December 18, 2024.
4 Forbes - What Is Variable Life Insurance Coverage? Content within this article is supplied for basic informative functions and is not supplied as tax, legal, health, or monetary advice for any person or for any particular situation.
For complete details, including accessibility and expenses of Aflac insurance, please contact your regional Aflac agent/producer. Aflac life prepares A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York City, Policies NY68200, NY68300 and NY68400.
IUL Benefits for Retirement
In Delaware, Policy A68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M.
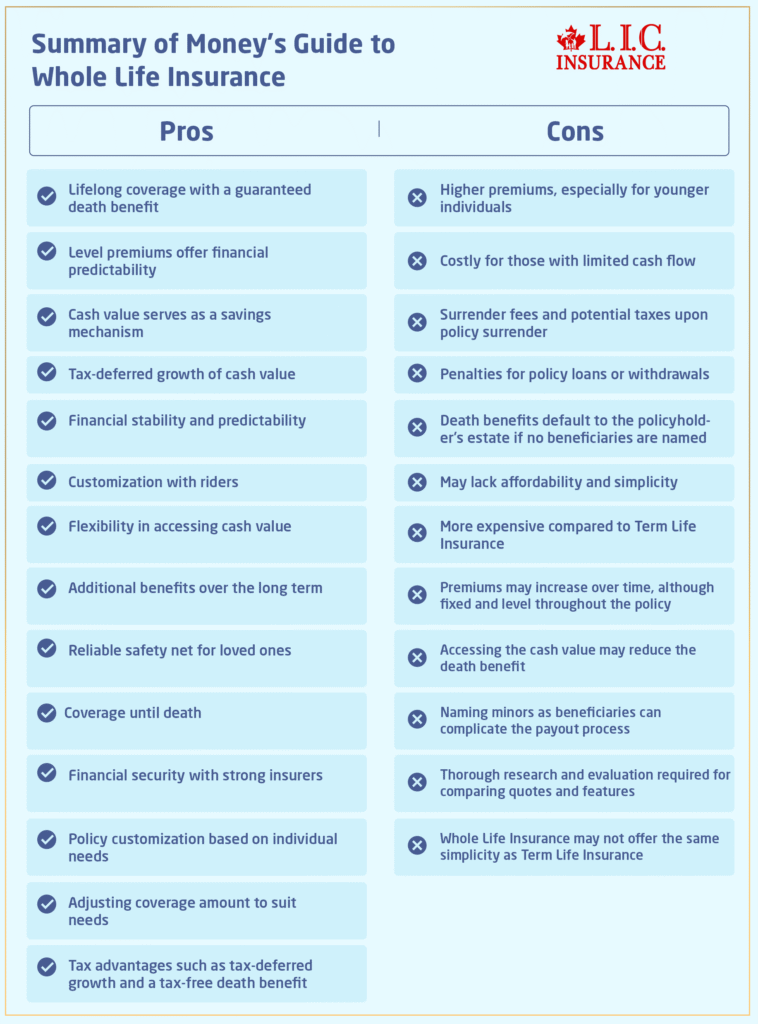
Coverage/plan levels might not be readily available in all states, including but not restricted to NM or VT. Benefits/premium rates might vary based on strategy picked. Optional riders may be available at an extra expense. Policies and riders might also consist of a waiting duration. Describe the exact policy and rider forms for advantage information, definitions, constraints and exclusions. In this article, we explain what whole life insurance is and compare it to term life insurance coverage, along with universal life and variable life insurance coverage. We also describe how entire life works and why many individuals choose it over term. Before we jump into this subject, we need to address one essential concern: What is entire life insurance? Simply put, it's a kind of insurance coverage that ensures coverage for the life time of the guaranteed as long as premiums are being paid. Entire life insurance coverage also guarantees the premiums and costs will never ever increase. Whole life insurance is one type of irreversible insurance coverage and is really different from term life insurance coverage, which offers protection for a given period just and does not build cash value. This short article discusses how whole life insurance works Lots of individuals consider life insurance coverage only in terms of a death advantage. Numerous of those functions, in some cases called living advantages, are highly preferable, andthis is importantthose features
Indexed Universal Life Benefits for Retirement
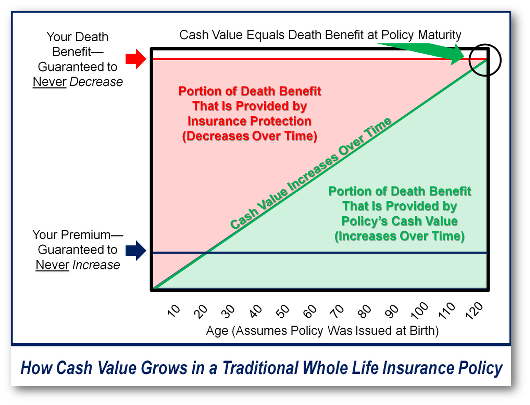
can not be found in any other type of monetary item on earth. If term life insurance is the most typical form of life insurance coverage, entire life insurance is the earliest type of permanent life insurance.(Two exceptions are suicide within the first 2 years, and pushing the insurance coverage application.)On the other hand,"term policies are mostly developed to last only for a limited period of time that will likely end before you pass away. "Having an insurance coverage that is guaranteed not to end before you do suggests that a policy you purchased to supply protection for your family will protect them, anytime you die. You'll also get a totally free chapter from Pamela Yellen's New York Times best-selling book on this subject.] Entire life insurance includes an element that term life insurance coverage does not have. Part of your premium approaches a savings portion of your policy. This is called the cash worth of your policy. This allows policies to be created so that no more premiums are due as soon as you retire. You can take out a loan at a rate that is typically lower than banks provide.
The larger your money worth, the larger the loan you can take. You can utilize your money value to supplement your other retirement earnings. Whole life insurance coverage is the only kind of life insurance coverage that guarantees of the following: The death advantage won't decrease The policy will not end as long as premiums are paid Your premiums won't
Term vs Whole Life Insurancego up Your expenses will never increase The insurer guarantees that the money worth of your entire life insurance coverage policy will grow with time. figure out how much your cash worth must grow based upon present rates of interest, which, of course, differ in time. enable you to invest funds in policy subaccounts, similar to shared funds. Your money value will increase ordecrease, depending on the efficiency of these subaccounts. What takes place if efficiency of the money value of your universal or variable life policy drops? Who has to ante up more superior to keep your policy in force? You do. Neither choice is excellent. If you have a whole life policy, you will not have to make those awful options. The premium, cash worth, and survivor benefit are all ensured. And did you understand you can discover precisely what your guaranteed premium, cash worth and survivor benefit will be at any moment before you decide if it makes sense to start a whole life policy? Simply ask for a FREE, no-obligation Analysis here to take the initial step. In such a way, it resembles getting an income tax refund. Now, dividends are not ensured. It's conceivable an insurer could have an awful, awful, no good, extremely bad year . That's what the company prepares for. And every year that'sbetter than they prepared, they can pay a dividend. Get Your FREE Report! Get instant access to the FREE 18-page Unique Report that exposes how super-charged dividend paying whole life insurance lets you bypass Wall Street, fire your lender, and take control of your monetary future. You get to tell the insurer what to do with your dividend. and this simply may be the neatest thing considering that cupcakesyou can have them utilize your dividend to purchase more insurance coverage for you insurance coverage you'll never ever have to pay another premium for once again. Consider that! You can buy extra insurance that's paid up, indicating no more premiums will be due on that additionever. If that advises you of the eighth wonder of the worldcompound interestthat's because the concept is precisely the same. Only paid up entire life insurance additions construct both your policy's cash value and your survivor benefit. You can find out more here about dividend-paying entire life insurance coverage, which lots of people discover particularly interesting. Term life insurance premiums go upsometimes drasticallywith every brand-new term, because much of the expense of insurance coverage is based on how most likely you are to die at a given age, and as you get older, that probability goes up. Universal and variable insurance coverage premiums can increase, tooagain, in some cases drasticallyif money worth drops dueto low interest rates or poor financial investment performance. So you may be asking, "If it costs more to guarantee my life with every death year, how can a life insurance coverage company guarantee my premiums will never ever go up?" The response is elegantly simpleand it assists discuss why whole life insurance coverage is more expensive than term insurance coverage in the early years of the policy.

Latest Posts

Finding Your Top 2026 Medicare Supplement Coverage

Maximizing IUL Growth Potential for Retirement
The Mechanics of Whole Life Coverage